By Ayomide Otitoju
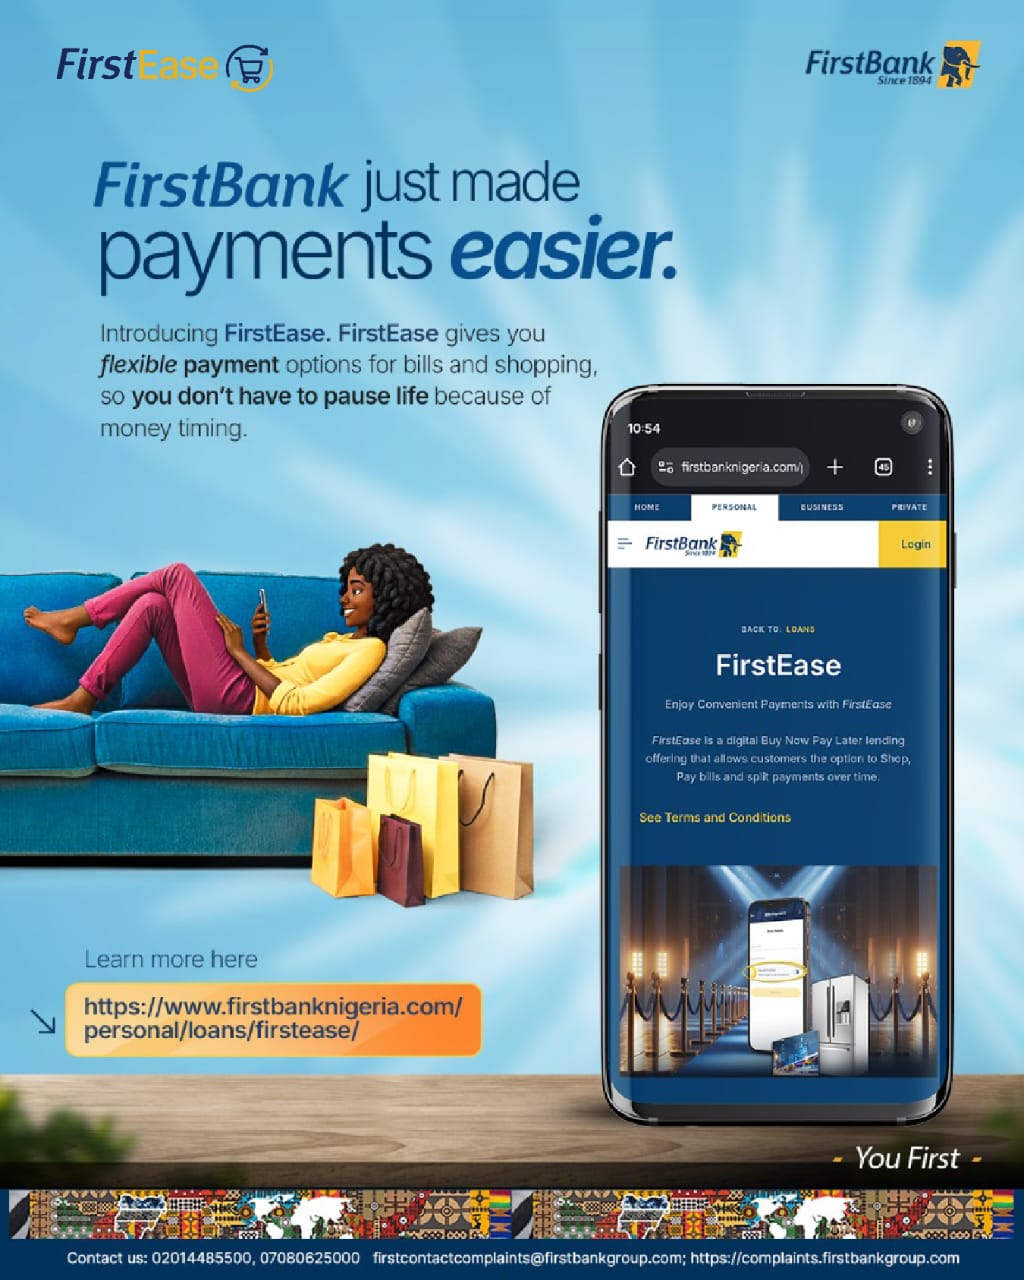
FirstBank has introduced FirstEase, a digital lending solution designed to help eligible customers finance selected purchases and bills through flexible repayment arrangements.
The product is FirstBank’s response to the growing Buy Now, Pay Later (BNPL) model, allowing customers to access selected products and services without paying the full cost upfront.
FirstEase operates through two main channels: FirstEase for e-commerce purchases and FirstEase for bill payments.
The solution is targeted at salary earners and other eligible customers seeking flexible ways to manage household purchases and expenses through digital channels and approved merchant platforms.
Financing gadgets and household appliances
Through its e-commerce offering, FirstEase enables eligible customers to purchase selected products from participating FirstBank partner merchants and repay the financed amount in instalments.
Partner platforms and merchants include Ringaz, Chamuze, Pointek, Webuyam, Electromall and Uwana Energy, as well as Klump, which aggregates merchants including Jumia, Konga and ShopAhome.
Eligible product categories include smartphones, laptops, tablets, televisions, refrigerators, washing machines, microwaves, sporting equipment, gadgets and other household essentials.
For e-commerce purchases, customers are required to make a minimum 30 per cent equity contribution, while FirstEase finances the balance. The facility has a repayment tenor of up to six months, with monthly repayments scheduled around the customer’s payday.
The maximum financing amount for the e-commerce option is ₦1 million.
FirstEase also covers bill payments
Beyond retail purchases, FirstEase provides financing for selected bills through FirstBank’s FirstMobile and LIT App.
Eligible customers can select a biller, enter the required information and activate the FirstEase option before completing the transaction.
The bill-payment facility covers services such as electricity, data, cable and airtime.
Unlike the e-commerce option, the bill-payment facility requires no equity contribution. Transactions range from ₦1,000 to ₦200,000 and have a 30-day repayment tenor.
The two options are therefore structured for different needs: e-commerce financing supports purchases from participating merchants, while the bill-payment option provides financing at the point of selected bill payments.
Digital application and eligibility assessment
FirstEase is designed to operate largely through digital channels.
For an e-commerce transaction, a customer selects an eligible product, proceeds to checkout, chooses FirstCheckout and then selects FirstEase. The customer’s account number is validated, eligibility is assessed and the customer selects a preferred repayment tenor.
Details of the required upfront contribution, monthly instalment and other repayment obligations are presented before the customer accepts the terms and completes the transaction.
FirstEase uses credit and affordability assessments to determine eligibility. According to the product information, the assessment considers FirstBank’s customer and credit records, including account activity, salary account status and a valid BVN.
The process also incorporates third-party credit scoring and artificial intelligence and machine-learning models to determine personalised eligibility amounts for the e-commerce and bill-payment facilities.
Repayment comes with charges and responsibilities
While BNPL facilities provide customers with additional flexibility, FirstEase customers are required to understand the applicable charges and repayment obligations before accepting an offer.
For e-commerce FirstEase, the applicable charges include three per cent interest per instalment on a reducing balance, a two per cent one-off insurance charge at disbursement and a FirstCheckout fee of 1.2 per cent, capped at ₦2,000.
For bill payments, customers are charged five per cent monthly interest and a three per cent monthly insurance charge.
FirstEase also provides repayment information and reminders, with automated collection features and SMS and email notifications ahead of payment due dates.
Customers can also access information about their outstanding obligations through available mobile channels.
Financing integrated into the digital payment journey
FirstEase connects financing directly to the purchase of a product or payment of a bill rather than providing customers with unrestricted cash.
FirstBank describes the facility as a point-of-sale financing solution that offers a streamlined application process and direct integration with participating merchants.
For eligible customers, the service provides another option for managing the cost of selected purchases and bills while spreading repayment over an agreed period.
As digital commerce and mobile payments continue to shape consumer behaviour, FirstEase integrates financing into the same digital journey, allowing customers to select products or bills, complete transactions and manage repayments through digital channels.
The facility, however, requires customers to consider the applicable charges, eligibility requirements and repayment obligations before using it.